When payments never stop, what does “intraday liquidity” really mean?
For years, banks have managed liquidity around a fairly clear operating rhythm. There is a start to the day, there are established windows and cut-off times, and there are moments when positions are reviewed, funding decisions are made and liquidity is moved where it is needed.
That model still exists, of course. But it is increasingly sitting alongside a very different reality.
Instant payment infrastructures operate 24/7. Money can move at any time, including nights, weekends and public holidays. At the same time, financial infrastructures continue to evolve and the industry is exploring new ways of moving value that are less dependent on traditional operating hours.
This raises a question that I find increasingly relevant: what happens to intraday liquidity management when the traditional idea of the “day” becomes less important?
The answer is probably more complex than simply having access to balances more frequently.
A liquidity position is constantly changing
Treasury teams have always needed to understand their liquidity position. What changes in a more continuous environment is the frequency and context in which that position can move.
Payments are constantly affecting it. Incoming funds increase available liquidity, outgoing payments consume it, and delays or unexpected flows can change what was anticipated.
When you add different accounts, currencies, banking relationships and payment infrastructures, getting a clear picture becomes more difficult. And it is not only a question of how much liquidity is available, but also where that liquidity is held and whether it can be moved to where it is needed at the right time.
Banks already have a huge amount of information available to them. The challenge I often see is bringing that information together in a way that helps people understand what is actually happening.
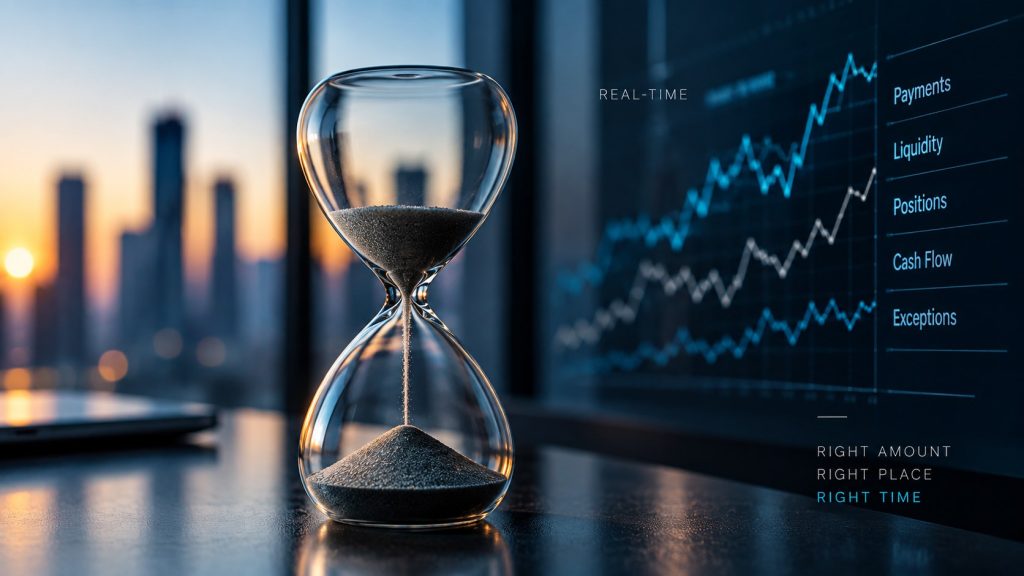
Knowing the balance of an account at a particular moment is useful. Knowing how the overall position is evolving, what is driving the change, how actual flows compare with what was expected and whether something requires attention gives Treasury and Operations a much more useful view.
This becomes particularly relevant when activity continues outside the traditional working day.
Payments and liquidity are closely connected
Payments and liquidity are often discussed separately. In practice, however, the relationship between them is very direct.
Payment activity ultimately has liquidity implications, although where and when those implications arise depends on the settlement model and infrastructure involved.
As instant payments become more widely used, this connection becomes even more important. A payment can be initiated and settled in seconds, but the institution still needs to ensure that liquidity is available in the right place to support that activity.
And the pattern of that activity may be different from what banks have traditionally managed.
What happens on a Saturday evening? How much liquidity should remain available overnight or over a weekend? How much needs to be positioned in advance to support continuous payment activity? How do you react when actual flows differ significantly from what was expected? How much liquidity is being held simply as a precaution?
This is also where the economics and risk implications become important. Holding too much liquidity can tie up funding, collateral and balance-sheet capacity unnecessarily, while holding too little, or having it in the wrong place, can create urgent funding needs, operational intervention and, in more severe cases, regulatory or reputational consequences. The challenge is therefore not simply to maximise liquidity, but to have the right amount, in the right place, at the right time.
These questions are becoming part of the wider discussion around instant payments. They are not only about having enough liquidity overall, but also about how that liquidity is distributed across accounts and infrastructures and how efficiently it can be mobilised.
They also bring Payments, Treasury and Operations closer together. Each team may look at the transaction from a different perspective, but they increasingly depend on a shared understanding of what is happening.
Having the information is only part of the equation
The financial industry has made significant progress in making information available faster. That is clearly positive.
But speed of information does not automatically make a decision easier.
If liquidity information is spread across several systems, accounts or infrastructures, teams may still need to piece together the situation before they can act. The same is true when information is technically available but lacks the context needed to understand whether a movement is normal or requires attention.
This is an area where I think there is still a lot of room for progress.
The useful questions are often quite practical. Where is liquidity available? How is the position changing? Are actual payment flows behaving as expected? Is there a potential shortfall developing somewhere? Does somebody need to take action?
Answering those questions consistently requires good technology, clear processes, appropriate controls and coordination between teams.
It also requires thinking about what happens outside normal operating hours. A 24/7 payment environment does not necessarily mean that every Treasury or Operations function suddenly needs to operate in exactly the same way around the clock.
But institutions do need to decide how those periods will be managed, which situations require intervention and what information people need when they have to make a decision. As payment activity becomes more continuous, automation may also play a greater role in monitoring positions, identifying exceptions and, where appropriate, helping to manage liquidity within predefined limits.
Where does intraday liquidity go from here?
I don’t think traditional liquidity management is going to disappear. Operating days, settlement windows and cut-off times will continue to be relevant across many parts of the financial system.
What is changing is that banks increasingly have to manage that world alongside infrastructures and services that do not follow the same timetable.
That coexistence is what makes this particularly interesting to me.
As more payment activity becomes 24/7, liquidity management will have to become more dynamic as well. Banks will need a clearer view not only of how payments affect their positions, but also of where liquidity is located, how actual activity compares with expected flows and how quickly liquidity can be mobilised when conditions change.
Perhaps we will continue to call all of this “intraday liquidity”. The terminology is not really the important part.
What matters is how banks adapt their operating models to a financial environment in which the end of the day increasingly does not mean the end of activity.
It is a topic I have been following closely for some time, and one I am particularly looking forward to discussing with the industry at Sibos in Miami.